How Due Diligence Underpins Credible Mineral Asset Valuation
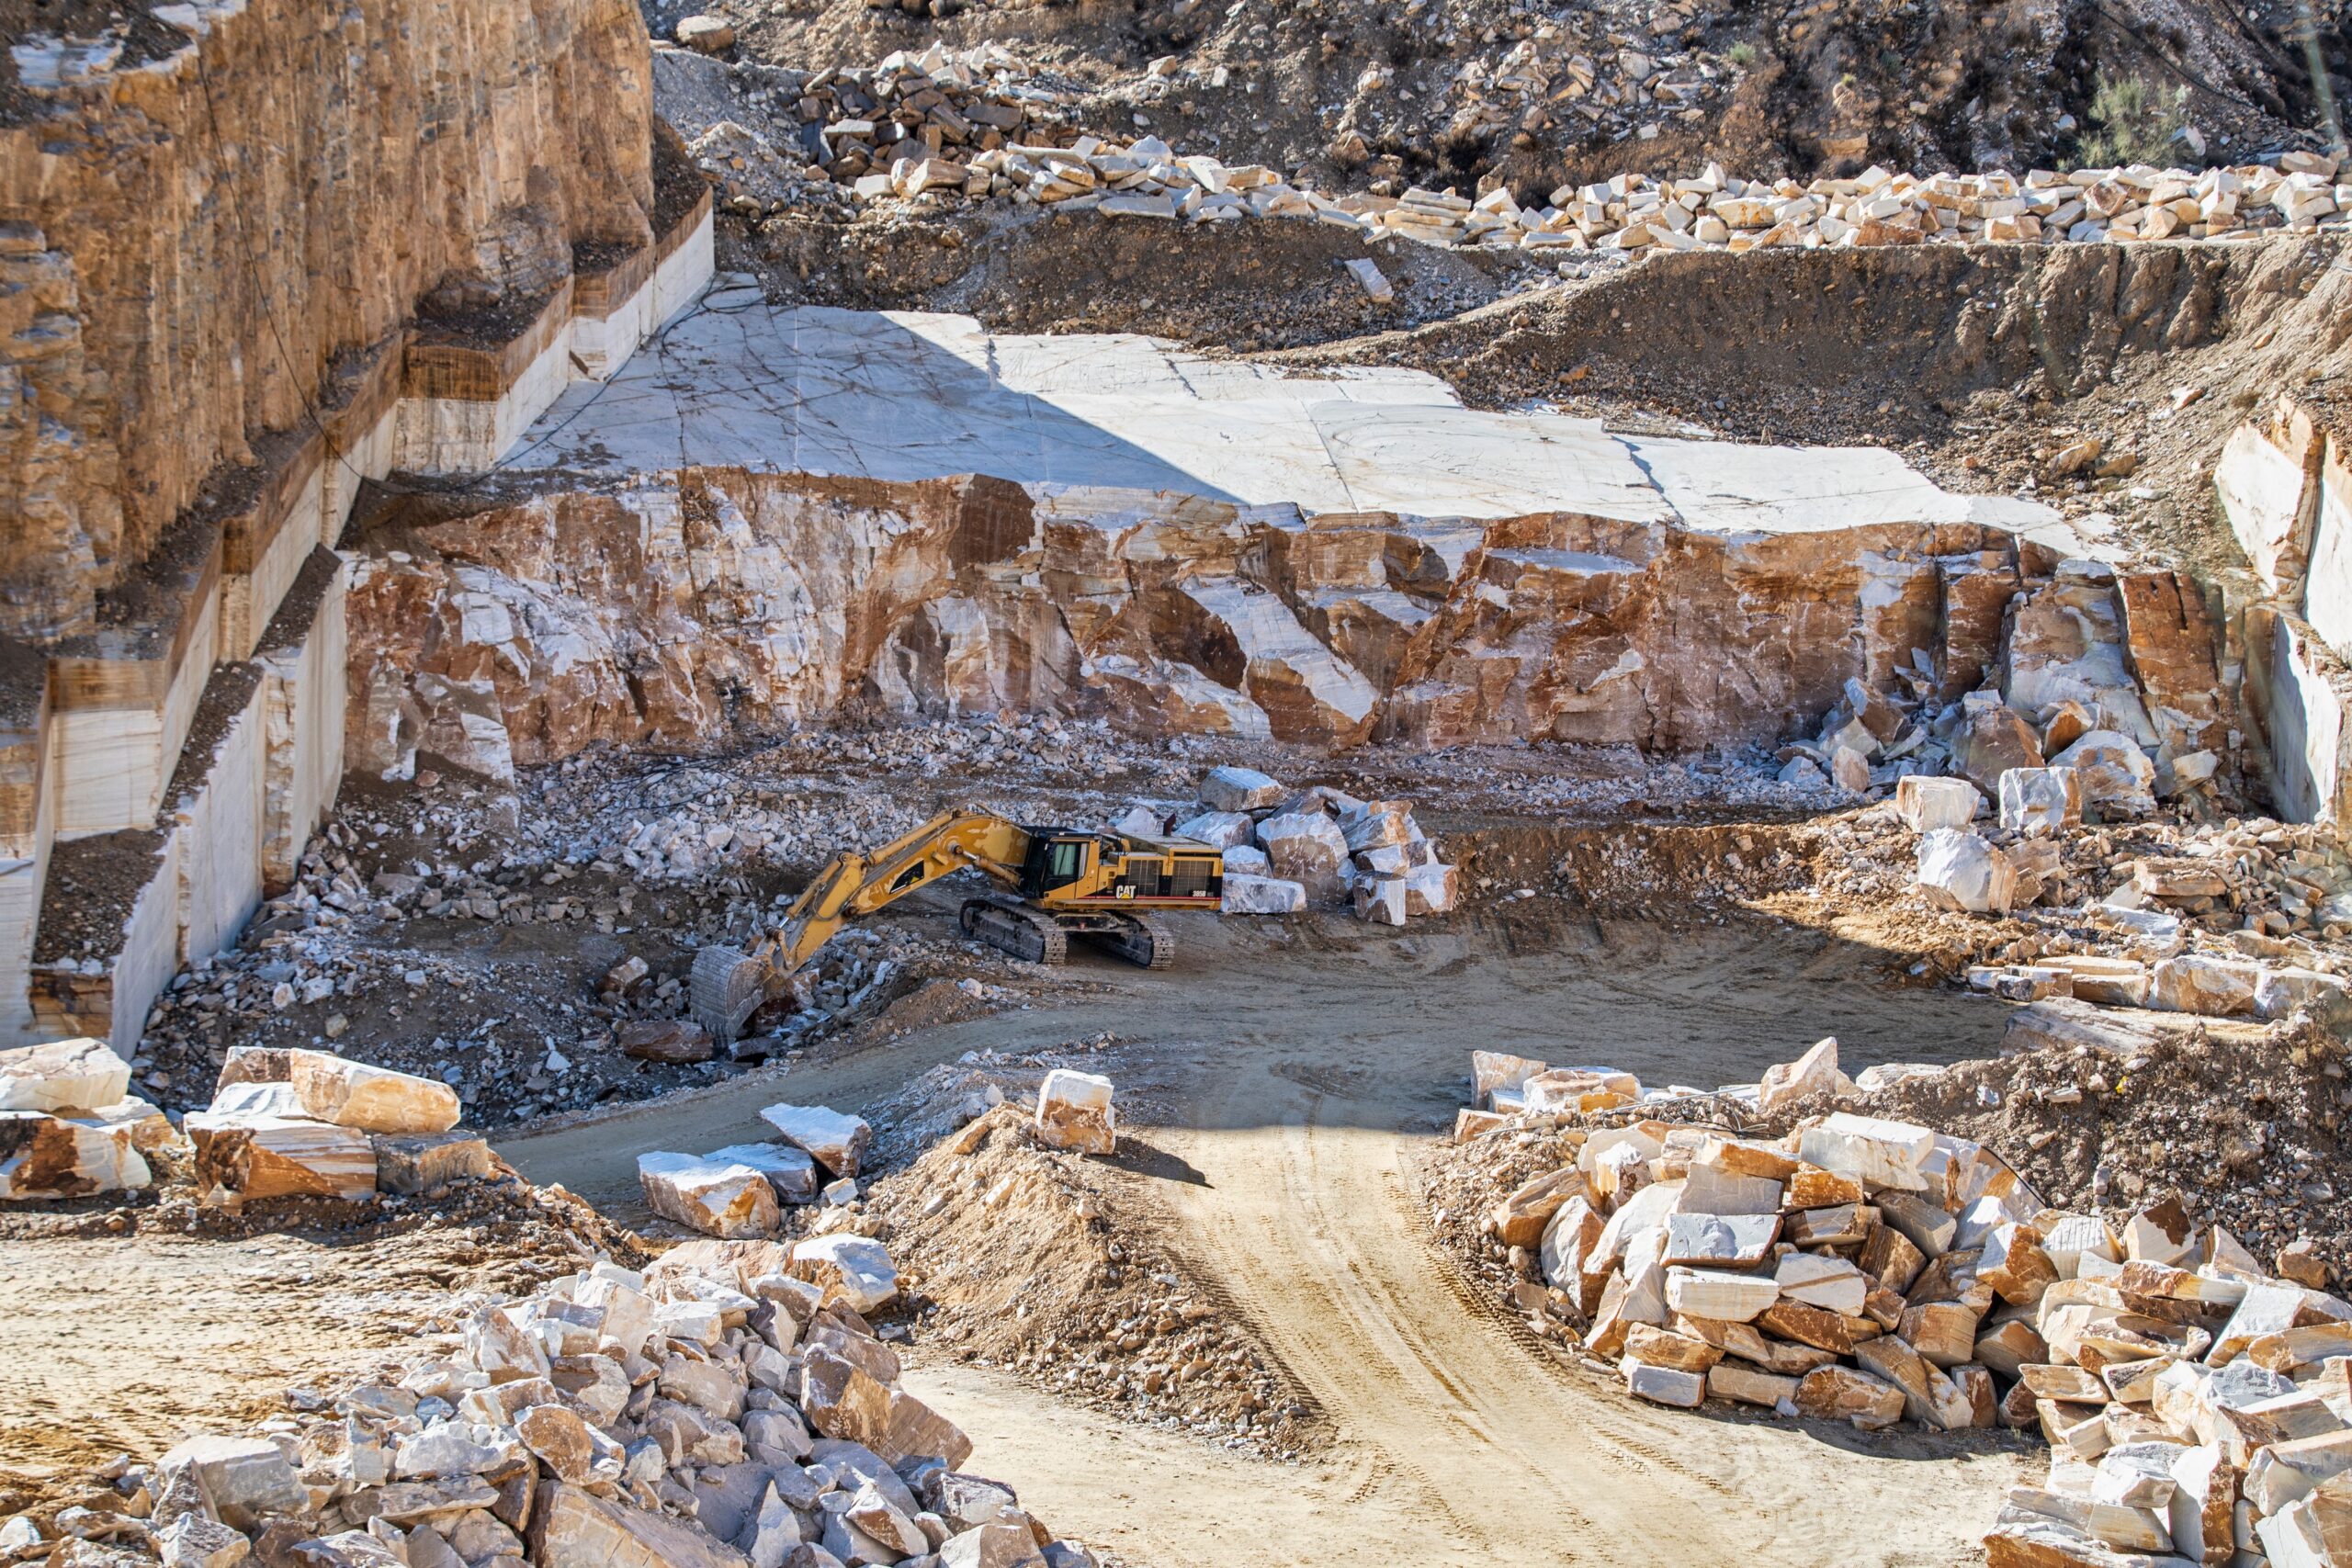
With fierce competition globally for investment capital, independent due diligence is essential for the credible and accurate valuation of mineral assets – even when not formally required by stock exchanges or lenders.
Sound valuation is a cornerstone of responsible mining investment, and is far more than a financial exercise. It is a comprehensive assessment that combines technical, commercial and economic data to realistically estimate a project’s value at a certain point in time. When supported by rigorous due diligence and multidisciplinary technical review, valuation provides confidence that investment decisions are based on sound evidence rather than optimism or assumption.
In the mining industry, mineral assets are the foundation on which investment decisions, project financing, mergers and acquisitions, and long-term business strategies are built. Yet determining the true value of those assets is far from straightforward. Mineral deposits are subject to geological uncertainty and are often technically complex, while fluctuating commodity markets and changing regulatory requirements also affect valuations.

Confidence is key
Mining companies require independent valuations for a range of reasons through the project life cycle. While commonly used to support stock exchange listings, mergers, acquisitions or equity fundraising, valuations are also vital for project financing, annual financial reporting, portfolio optimisation or strategic decisions on whether to develop, retain or divest an asset.
Each of these situations demands confidence that the value assigned to a mineral asset reflects both its technical reality and its commercial potential. Investors, banks and other financial institutions invariably expect valuations to withstand detailed scrutiny before committing capital.
A credible valuation therefore provides an independent assessment of whether the assumptions underlying a project are reasonable, transparent and supported by evidence. It demonstrates that the estimated value has been derived through recognised methodologies rather than commercial expectation or management ambition.
Drawing on all disciplines
No single professional discipline possesses all the expertise required to undertake comprehensive mineral valuation. Rather than producing isolated technical opinions, the various specialists collectively build a coherent understanding of project risk, ensuring that financial valuation remains firmly grounded in operational reality.
Each specialist contributes critical information that ultimately influences financial outcomes, by collectively determining whether projected cash flows are realistic. For instance, geologists assess the quality of exploration data, sampling methodologies, resource estimation procedures and geological confidence. Mining engineers evaluate mine design, production schedules, modifying factors and operating assumptions. Metallurgists confirm processing recoveries and plant performance expectations. Environmental specialists assess rehabilitation liabilities, permitting obligations and closure costs. Specialists may also be required to examine project risks arising from infrastructural, geotechnical and hydrogeological factors.
Even seemingly minor technical issues can materially alter project economics. There may be environmental liabilities which have not been fully recognised, or infrastructure constraints that could affect production schedules; similarly, land access complications or uncertainty regarding mineral rights may also influence project value. The strength of a multidisciplinary approach to due diligence lies in its ability to identify these issues before investment decisions are made.
Neutral ground
One of the defining characteristics of independent valuation is objectivity. Mining companies often possess highly capable internal technical teams that perform valuations for portfolio management and strategic planning purposes. Internal assessments remain valuable management tools, particularly when comparing competing development opportunities or prioritising capital allocation.
However, where material transactions are involved – such as public listings, acquisitions, significant financing or major corporate restructuring – independent assessment provides an additional layer of confidence for external stakeholders. The independence of a due diligence study helps demonstrate that valuation conclusions have not been influenced by commercial pressures or corporate expectations. Instead, they reflect professional judgement applied within recognised valuation frameworks using transparent assumptions that can be independently examined.
Ultimately, the purpose is not simply to produce the highest or lowest possible valuation depending on commercial interests. The objective is to determine a realistic and defensible value that accurately reflects the technical characteristics and commercial prospects of the asset.
Reflecting uncertainty
It is important to understand that a good mineral valuation delivers a defensible estimate rather than an exact answer. In reality, every valuation represents an estimate based on information available at a particular point in time. However, commodity prices are always changing, exchange rates fluctuate, operating costs evolve, geological knowledge improves and market conditions shift continuously.
Consequently, valuation is not about predicting the future with precision but about developing a reasonable estimate that reflects current knowledge while recognising uncertainty. Sensitivity analysis therefore forms an important component of responsible valuation practice. Testing projects against different commodity price forecasts, discount rates, operating costs and development assumptions helps establish whether the project remains economically robust under varying market conditions.
Rather than weakening a valuation, acknowledging uncertainty strengthens its credibility by demonstrating that conclusions have been tested against realistic alternative scenarios.
Good information
Perhaps the greatest practical challenge during valuation is not necessarily analytical complexity but obtaining complete and reliable information. Mining companies frequently provide extensive documentation, yet important technical information may still be incomplete, inconsistent or interpreted differently by various project teams.
This challenge is particularly evident among junior mining companies or new entrants to the mining sector, where management teams may not fully appreciate the breadth of information required for a comprehensive valuation. Successful due diligence therefore becomes an iterative process. Technical specialists work closely with clients to clarify information requirements, identify data gaps and understand the assumptions underpinning existing studies.
Here, the objective is not to create unnecessary complexity but to ensure that valuation conclusions rest on sufficiently robust evidence. Where information remains incomplete, experienced valuators apply professional judgement, supported by recognised valuation methodologies, transparent assumptions and appropriate sensitivity analysis. Equally important, these assumptions need to be clearly documented so that users of the valuation understand both the strengths and limitations of the conclusions reached.
Cost of getting it wrong
The consequences of poor valuation extend well beyond an inaccurate number in a report. Overvalued projects can distort investment decisions, encourage excessive capital expenditure, undermine financing negotiations and ultimately destroy shareholder value when expectations are not achieved.
Conversely, undervalued assets may result in companies accepting unfavourable transaction terms, delaying viable developments or failing to secure investment that otherwise could have advanced the project.
Regulators and stock exchanges also expect valuation reports supporting public disclosures to comply with recognised professional standards (see sidebar). Where deficiencies are identified, companies may be required to revise public reports, withdraw technical disclosures or face disciplinary action affecting both corporate reputation and the professionals responsible for the work.
Beyond the regulatory consequences, inaccurate valuations erode confidence among investors, lenders, customers and strategic partners. Rebuilding that trust is often considerably more difficult than producing a robust valuation in the first place.
Due diligence on valuation
In summary, due diligence tests the technical foundations that support the financial value assigned to a mineral asset. It involves examining whether the geological information is reliable, whether resource and reserve estimates are appropriately supported by sampling and quality assurance processes, and whether mine plans are practical. It also assesses whether processing recoveries are achievable and whether environmental obligations, infrastructure constraints and legal tenure have been adequately considered.
This independent and multidisciplinary approach to valuation helps protect a company’s credibility by ensuring that mineral assets are valued in a way that reflects both current reality and future opportunity.
Combining diligence and objectivity
Independent mineral asset valuation is most effective when it combines robust technical due diligence with objective financial assessment to:
- Reduce the risk of overstating or understating a project’s worth
- Improve investment decisions
- Raise confidence among investors, lenders and strategic partners
Multidisciplinary expertise is vital, to evaluate technical assumptions relating to geology, mining, metallurgy, environmental obligations and market conditions.
An independent valuation should produce a transparent, reasonable and defensible estimate that accurately reflects the asset’s technical realities, commercial potential and associated risks.
Frameworks for mineral reporting
Mineral asset valuation is guided by internationally recognised reporting and valuation frameworks that promote consistency, transparency and investor confidence.
Mineral resources and reserves are generally reported under codes aligned with the Committee for Mineral Reserves International Reporting Standards (CRIRSCO). This global body provides a template that underpins national reporting standards including:
- South African Code for the Reporting of Exploration Results, Mineral Resources and Mineral Reserves (SAMREC)
- Joint Ore Reserves Committee (JORC) in Australasia
- Pan-European Reserves and Resources Reporting Committee (PERC) in Europe
Among the other national codes are National Instrument (NI) 43-101 in Canada and the US Securities and Exchange Commission regulation S-K 1300 in the United States – serving similar disclosure purposes within their respective jurisdictions.
Valuation itself is governed by codes that fall under the International Mineral Valuation Committee (IMVAL). These include:
- South African Code for the Reporting of Mineral Asset Valuation (SAMVAL)
- Australasian Code for Public Reporting of Technical Assessments and valuations of Mineral Assets (VALMIN) in Australia
- The CIMVAL Code for the Valuation of Mineral Properties in Canada
- Society for Mining, Metallurgy & Exploration (SME) valuation standards in the United States
Together, these frameworks establish principles for competency, independence, transparency and reasonableness, helping ensure that mineral asset valuations are technically defensible and internationally credible.
Share this content: